
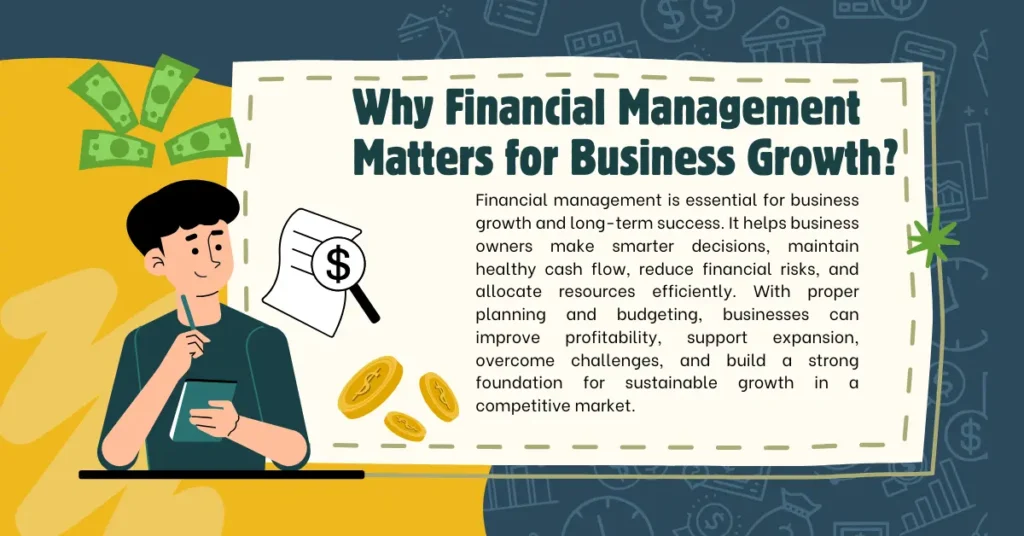
Financial planning is one of the most important parts of running a successful small business. Whether an entrepreneur operates a local shop, an online store, a consulting company, or a growing startup, financial decisions influence almost every aspect of daily operations.
Many small business owners concentrate heavily on generating sales. Although revenue is essential, it does not automatically mean that a business is financially healthy. Expenses, outstanding payments, taxes, borrowing costs, and available cash all influence the company’s ability to operate.
Developing a practical financial management system can help entrepreneurs understand their financial position, prepare for unexpected expenses, and make better decisions about future growth.
1. Understand the Difference Between Revenue and Profit
One of the first financial lessons every entrepreneur should understand is the difference between revenue and profit.
Revenue represents the money a business earns from selling products or providing services. Profit is what remains after relevant expenses have been deducted.
For example, imagine an online business generates $15,000 in monthly sales. Its expenses include inventory, advertising, shipping, software, and payment processing fees.
If these expenses total $12,000, the business has $3,000 remaining before considering any additional applicable taxes or costs.
This distinction matters because increasing sales does not always improve profitability. A company might experience rapid revenue growth while spending too much on advertising, discounts, or operating expenses.
Business owners should regularly review both revenue and profit to understand whether their operations are financially sustainable.
2. Create a Realistic Monthly Budget
A business budget provides a clear picture of expected income and expenses. It also helps owners decide how much money can reasonably be allocated to different activities.
Start by identifying fixed expenses. These may include rent, insurance premiums, employee salaries, and recurring software subscriptions.
Next, calculate variable expenses such as inventory, packaging, delivery, transaction fees, and advertising costs.
Once these figures are available, estimate expected monthly revenue using realistic assumptions rather than overly optimistic projections.
A useful budget should also include an allowance for unexpected expenses. Equipment failures, delayed customer payments, and sudden increases in supplier prices can affect operations.
Review the budget at least once a month. Comparing actual spending with planned spending makes it easier to identify problems before they become serious.
3. Maintain Healthy Cash Flow
Cash flow describes the movement of money into and out of a business.
A company can appear profitable on paper while struggling to pay its immediate bills. This can happen when customers purchase products or services on credit but delay payment.
Entrepreneurs should monitor outstanding invoices and establish clear payment terms. Sending invoices promptly and following up professionally can reduce unnecessary delays.
It is also useful to negotiate reasonable payment arrangements with suppliers where possible.
Another effective practice is maintaining a cash reserve. The appropriate amount depends on operating expenses, business risks, and income stability, but having accessible funds can provide valuable protection during difficult periods.
Cash flow forecasts can help business owners anticipate potential shortages and prepare before they occur.
4. Separate Personal and Business Finances
Mixing personal and business transactions creates unnecessary accounting difficulties.
A dedicated business bank account makes it easier to track company income, expenses, and payments. It also supports more organized financial reporting.
Business owners should maintain records of purchases, sales, invoices, receipts, loan payments, and other important transactions.
Accurate bookkeeping helps when preparing tax documents, evaluating profitability, or discussing financing options.
Entrepreneurs who are unfamiliar with accounting requirements may benefit from working with a qualified accountant or bookkeeper.
5. Understand Business Credit Before Applying for Financing
Business credit can become an important part of a company’s financial foundation.
A well-maintained business credit profile may help eligible companies access certain financing products, establish supplier relationships, or demonstrate financial responsibility.
However, building business credit requires more than applying for multiple accounts.
Owners should first establish the appropriate business structure, maintain accurate registration information, obtain the necessary tax identification details, and open a dedicated business bank account where applicable.
They should then research which suppliers and financial institutions report payment activity to relevant business credit bureaus.
Payment history matters. Making payments according to agreed terms and checking business credit reports for errors can support responsible credit management.
Borrowing should always be evaluated carefully. Interest rates, repayment schedules, fees, and the company’s ability to meet future obligations deserve attention before accepting financing.
6. Explore Funding Opportunities Carefully
Small businesses may need external funding to purchase equipment, expand operations, hire employees, or develop new products.
However, traditional loans are not the only possible source of funding.
Depending on eligibility and availability, entrepreneurs can investigate:
- Government and private business grants.
- Small business loans.
- Equipment financing.
- Business lines of credit.
- Crowdfunding opportunities.
- Strategic partnerships.
- Investment from suitable business investors.
Every funding option has different requirements and potential disadvantages. Grants may involve strict eligibility criteria, while loans create repayment obligations.
Entrepreneurs should research the conditions carefully and avoid assuming that an advertised funding opportunity is guaranteed.
7. Use Educational Resources to Improve Financial Knowledge
Financial decisions can become complicated, particularly for first-time entrepreneurs. Learning about budgeting, credit, business banking, taxes, and funding can help owners approach these responsibilities with greater confidence.
Organized educational platforms can make it easier to explore different subjects without relying entirely on scattered information.
Business owners looking for practical material on financial management, business growth, and company setup can find more tips here.
8. Review Financial Performance Regularly
Financial planning should not be treated as a one-time activity.
Review key performance indicators such as monthly revenue, gross profit margin, operating expenses, outstanding invoices, available cash, and debt obligations.
Comparing results across different months can reveal patterns and help owners identify areas that need attention.
For example, if customer acquisition costs are increasing while sales remain unchanged, the marketing budget may require closer evaluation.
Conclusion
Strong financial management gives small businesses a better foundation for stability and responsible expansion. By maintaining accurate records, monitoring cash flow, understanding business credit, and evaluating funding options carefully, entrepreneurs can make more informed decisions.
The goal is not simply to earn more money. It is to build a business that can manage its obligations, respond to unexpected challenges, and support sustainable development over time.


